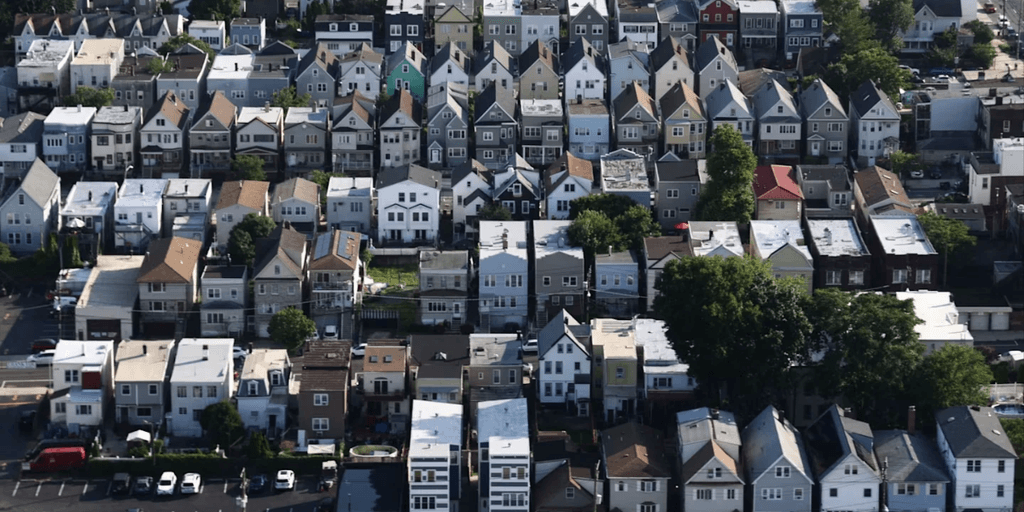
The national decline in signed home-sale contracts highlights how borrowing costs can influence major financial decisions for American households.
Housing demand loses momentum
Pending home sales declined across the United States in September as rapidly rising mortgage rates placed additional pressure on prospective buyers.
The National Association of Realtors reported that its Pending Home Sales Index fell 7.3% from August and 11.3% from a year earlier. All four major U.S. regions recorded declines on both measures.
The index tracks homes under contract before the transactions are completed, making it an early indicator of residential market activity.
The decline is relevant to households considering homeownership because buying a property involves several financial decisions at once. Buyers must evaluate their income, savings, borrowing capacity and ability to cover recurring housing expenses.
For working adults supporting families or planning a major move, a change in mortgage rates can affect whether purchasing a home remains practical.
Borrowing costs shape affordability
Mortgage rates influence monthly payments and the total cost of financing a property. When rates rise, borrowers generally pay more for comparable loan amounts.
That can force prospective buyers to reconsider the price range they can afford. Some may look for smaller properties, expand their search to other neighborhoods or delay purchasing while building additional savings.
The calculation extends beyond the mortgage itself. Property taxes, insurance, utilities, maintenance and unexpected repairs all affect a household's ongoing expenses.
A home that appears affordable based on its asking price may place significant pressure on a monthly budget once these costs are included.
For households with children, commuting expenses, education costs and other family commitments can further influence the amount available for housing.
Why the regional picture matters
The September pending-sales index declined in the Northeast, Midwest, South and West. The West recorded the largest monthly drop, followed by the South, Midwest and Northeast.
Although the overall pattern was national, local conditions remain important. Employment opportunities, wages, construction activity and the availability of homes differ from one region to another.
A household considering relocation may find that a lower purchase price comes with higher transportation costs or fewer suitable employment opportunities. Conversely, a more expensive market may offer different employment and commuting advantages.
Comparing the complete cost of living can therefore be more useful than evaluating housing prices alone.
Implications for household finances
A home purchase can affect a household's financial flexibility for years. Buyers need to consider whether they can manage mortgage payments while maintaining savings for emergencies and future expenses.
Lenders assess applications using their own qualification standards, but loan approval does not necessarily mean that every household expense will fit comfortably within a buyer's preferred budget.
The decline in pending sales also has implications for homeowners considering a move. Selling one property and purchasing another involves transaction costs, financing decisions and the possibility of obtaining a different mortgage rate.
Some owners may decide to postpone moving if the financial trade-offs are unfavorable.
Effects beyond the housing market
Residential transactions support a network of businesses, including mortgage lenders, inspectors, contractors, movers and retailers selling household goods.
When fewer contracts are signed, those businesses may eventually experience changes in demand. However, the size and timing of any effect depend on whether pending transactions proceed to closing and how other market activity develops.
The September report does not establish that home prices will decline or that all buyers have stopped purchasing properties. It identifies a reduction in contracts during a particular month.
A reminder to assess the full cost
The latest housing data underline the relationship between borrowing costs and household purchasing power. A decline in pending sales across all four regions suggests that financing conditions were affecting buyer activity beyond individual local markets.
For households, the key consideration is whether a purchase remains sustainable after accounting for the complete cost of ownership. For businesses, pending sales provide an early measure of consumer activity connected to residential property.
The figures offer a useful snapshot of market conditions, but future trends will depend on mortgage rates, employment, income growth, inventory and the financial circumstances of prospective buyers.

Men’s Insider Contributor
Nicole Warren
Covers entrepreneurship, career growth, and business trends with accessible insights for a broad audience.
This article features partner, contributor, or branded content from a third party. Members of the Men’s Insider editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.